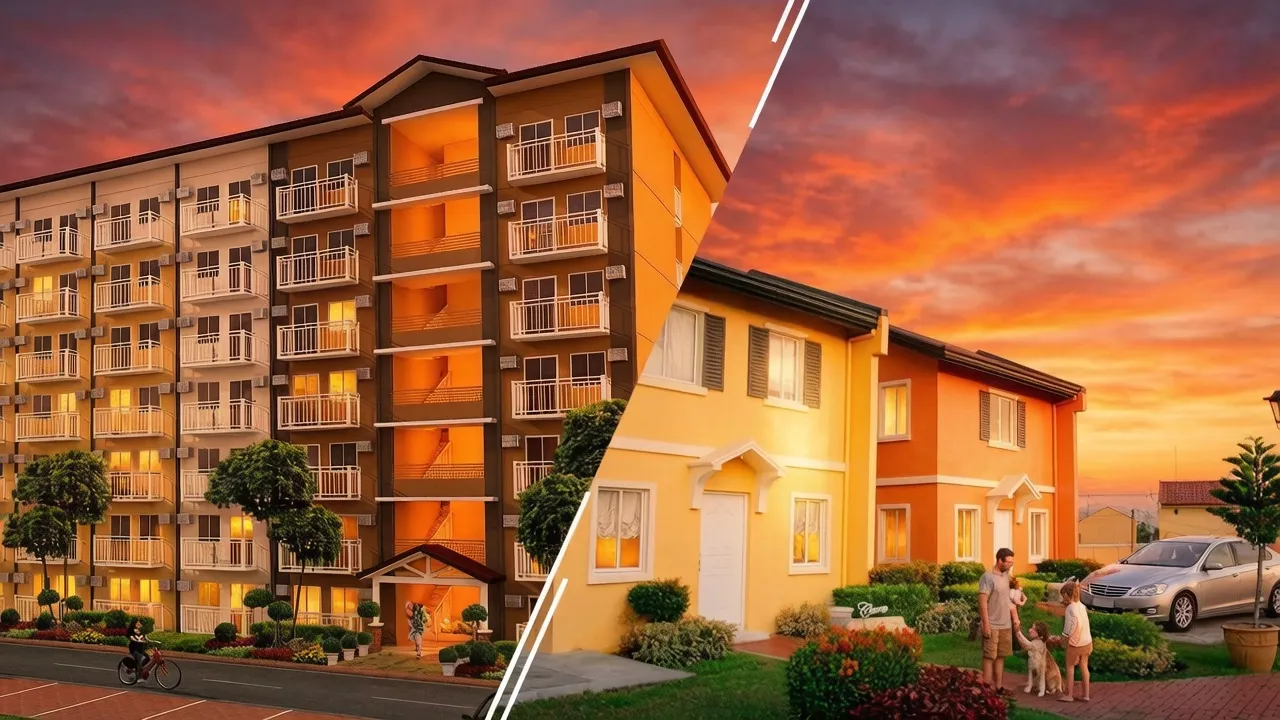
Choosing between a condo and a house and lot is one of the most consequential financial decisions a Filipino homebuyer makes. Both property types serve different life stages, budgets, and priorities, and the right fit depends less on which option is objectively better and more on which one matches your actual living situation.
This guide walks through ownership structure, real cost of ownership, location tradeoffs, maintenance, appreciation potential, and financing, so you can weigh both property types against your own budget and timeline.
Key Takeaways
- A condo buyer owns the unit and a share of common areas. A house and lot buyer owns the structure and the land title outright.
- Condos generally carry a lower upfront price, but monthly association dues continue indefinitely, even after the mortgage is paid off.
- House and lot properties tend to appreciate faster over the long term because land value drives most of the gain.
- Both property types can be financed through Pag-IBIG, bank loans, or developer in-house terms, though loan ceilings and interest rates vary by route.
- The right choice comes down to commute tolerance, space needs over the next three to five years, and how much maintenance you want to handle yourself.
Ownership Structure: What You're Actually Buying
A condominium purchase gives you title to your individual unit, plus a proportional share in common areas: hallways, elevators, the lobby, and amenity spaces. You do not own the land beneath the building. A house and lot, by contrast, transfers both the structure and the land title to you outright.
This distinction matters for resale, inheritance planning, and long-term equity, since land in the Philippines has historically appreciated independently of the structure sitting on it.
Condo vs House and Lot at a Glance
The factors below are the ones that most often decide the choice for first-time buyers. Weigh them against your own budget and timeline rather than treating any single row as the deciding factor.
| Factor | Condo | House and Lot |
|---|---|---|
| Upfront cost | Generally lower, no land cost | Generally higher, includes land |
| Recurring fees | Monthly association dues, indefinite | Real property tax, HOA fee if in a subdivision |
| Land ownership | No, unit and common-area share only | Yes, structure and land title |
| Typical location | Urban centers, near business districts | Suburbs and provinces, farther from the city |
| Maintenance | Handled by building management | Owner's full responsibility |
| Renovation freedom | Limited, needs management approval | Full, subject to local permits |
| Long-term appreciation | Strong in prime districts, shorter cycles | Historically stronger, driven by land value |
Upfront Cost and Total Cost of Ownership
Condo units in Metro Manila and other urban centers generally carry a lower entry price than a comparable house and lot in the same area, partly because you are not paying for land. Pre-selling terms with staggered downpayments make condos accessible earlier in a buyer's career.
House and lot packages tend to require a larger downpayment, particularly for finished, ready-for-occupancy units close to city centers. Developments farther from Metro Manila, in provinces like Bulacan, Cavite, Laguna, or Rizal, close that price gap considerably.
The total cost picture shifts once recurring fees enter the picture. Condo owners pay monthly association dues indefinitely, covering building security, common area maintenance, and amenity upkeep. House and lot owners skip association dues, unless the property sits inside a gated subdivision with its own homeowners association, but absorb the full cost of repairs, landscaping, and exterior maintenance themselves.
Location and Daily Commute
Condo developments cluster around business districts, transport hubs, schools, and hospitals, which is why they are the default choice for professionals who prioritize a short commute. A house and lot within the same budget usually sits farther out, trading proximity for space.
Infrastructure projects like new expressways and rail extensions are gradually narrowing that gap for provincial developments, but commute time remains one of the clearest dividing lines between the two property types. The map below shows the pattern directly: condo towers packed tightly inside Metro Manila's business districts, against house and lot developments spread across the outlying provinces that most buyers compare them to.
Condo listings near Metro Manila
House and lot listings across the wider region
The pattern holds across the country, not just in the map above. A few cities and provinces consistently show up on one side of the condo vs house and lot split:
Where condos dominate
- Makati City, the country's original central business district
- Taguig City, home to Bonifacio Global City's high-rise corridor
- Pasig City, anchored by the Ortigas Center business district
- Mandaluyong City, sandwiched between Makati and Ortigas
- Quezon City, with dense clusters near its own business districts
- Cebu City, the largest condo market outside Metro Manila
Where house and lot dominates
Space, Privacy, and Customization
Typical condo units in the Philippines average around 50 square meters or less, and any renovation beyond cosmetic changes requires approval from building management. Structural modifications are usually off the table entirely.
A house and lot gives you full control over both indoor and outdoor space. Owners can expand, renovate, add a second or third floor, or build a garden without seeking approval from a condo corporation, subject to standard local government permits. For growing families or anyone planning multi-generational living, this flexibility is often the deciding factor.
Maintenance and Security
Condo living shifts most of the maintenance burden to the building's management team, who handle security personnel, CCTV monitoring, fire systems, and upkeep of shared facilities in exchange for the monthly dues. This is a meaningful advantage for buyers who do not want to manage repairs directly or who travel frequently.
House and lot owners are responsible for everything: roof repairs, plumbing, pest control, and their own security arrangements, unless the property is inside a subdivision with a guardhouse and perimeter security. That said, homeowners in a subdivision often report a stronger sense of community through neighborhood associations and shared events, something high-rise condo living rarely replicates.
Appreciation Potential and Resale Value
Land has historically appreciated faster than structures in the Philippine market, which gives house and lot properties an edge for long-term wealth building, particularly in areas near planned infrastructure. Condos in prime, high-demand districts can still see strong short-term appreciation, and their smaller footprint and lower price point often make them easier to rent out or resell quickly to young professionals entering the market.
Financing Options: Pag-IBIG, Bank Loans, and In-House Terms
Both property types can be financed through Pag-IBIG Fund, bank housing loans, or a developer's in-house financing. Pag-IBIG tends to offer the most competitive interest rates but comes with loan ceilings that may fall short of financing a mid- to high-end condo or house and lot in full. Bank financing covers larger gaps but at higher interest rates, and in-house financing from the developer is often faster to secure but comes with steeper monthly amortization over a shorter term.
Buyers weighing a condo against a house and lot should run the numbers on all three financing routes before committing to either property type.
The Acquisition Process: Condo vs House and Lot
The first three steps of buying either property type look identical: reserve, sign, and get financing approved. The process only splits once the unit or the house is ready to hand over, which is where a condo purchase and a house and lot purchase start requiring different documents and produce a different kind of title.
Matching the Decision to Your Life Stage
A few questions cut through most of the back-and-forth:
- Where do you actually spend your week? If work, school, and errands are concentrated in the city, the shorter commute a condo offers has real value.
- How much space do you need in the next three to five years? A single professional or couple may be comfortable in a well-designed unit; a family with children usually outgrows condo living faster than expected.
- Are you buying to live in it, rent it out, or hold it as a long-term asset? Condos in accessible urban areas tend to attract steady rental demand. House and lot properties in growing suburban corridors tend to build equity through land value over time.
- How much maintenance are you willing to take on yourself? Condo association dues buy convenience. House and lot ownership buys control at the cost of hands-on upkeep.
Frequently Asked Questions
Is a condo cheaper than a house and lot in the Philippines?
Usually, at the upfront purchase price. Condo units skip the cost of land, which lowers the entry price compared to a house and lot in the same area. Once monthly association dues are factored in over the life of ownership, the gap narrows.
What is the biggest ownership difference between a condo and a house and lot?
A condo buyer owns the unit plus a share of common areas, but not the land beneath the building. A house and lot buyer owns both the structure and the land title outright.
Do condo owners pay association dues forever?
Yes. Association dues continue for as long as you own the unit, even after the mortgage is fully paid off, since they cover ongoing building security, common area maintenance, and shared amenities.
Which appreciates faster, a condo or a house and lot?
Land has historically appreciated faster over the long term, giving house and lot properties an edge for generational wealth. Condos in prime, high-demand districts can still see strong short-term appreciation and tend to be easier to resell or rent quickly.
Can I use Pag-IBIG financing for either a condo or a house and lot?
Yes, Pag-IBIG Fund financing applies to both property types. Loan ceilings may fall short of covering a higher-priced condo or house and lot in full, in which case buyers combine it with bank financing or a developer's in-house terms.
How much living space does a typical Philippine condo unit have?
Most condo units average around 50 square meters or less, and structural renovations generally require approval from building management.
Is a house and lot better for a growing family?
Often, yes. A house and lot offers more indoor and outdoor space, room to expand or renovate without management approval, and land ownership that can be passed down, all of which tend to matter more as a family grows.
What ongoing costs should I expect with a house and lot?
Real property tax, plus full responsibility for repairs, landscaping, and security. Houses inside a gated subdivision may also carry a homeowners association fee, though typically lower than condo association dues.
Ready to start comparing listings?
Browse real estate developers and brokers on azifind, or check financial services providers to compare Pag-IBIG, bank, and in-house financing options before you commit.